What is the scope and industry significance of the Pharmacies and Drug Stores Market?
Our analysis indicates that the Pharmacies and Drug Stores Market encompasses retail dispensaries, compounding facilities, and clinical outlets supplying prescription drugs, OTC formulations, and specialized health products. Valued at 1383.63 Billion in 2026, this sector represents the vital frontline of healthcare delivery, bridging pharmaceutical manufacturers with patients via critical logistics networks and patient-centric care models.
Key market drivers, restraints, challenges, and opportunities shaping Pharmacies and Drug Stores Market
The market thrives on aging global demographics and rising chronic disease prevalence, though it faces severe margin pressures from reimbursement cuts by pharmacy benefit managers. Opportunities lie in expanding clinical services and specialty drug dispensing, while supply chain bottlenecks for active pharmaceutical ingredients remain a persistent operational restraint for major operators.
Emerging trends and growth patterns in Pharmacies and Drug Stores Market
The industry is experiencing a massive pivot toward omnichannel healthcare delivery, blending brick-and-mortar retail with digital prescription refills and telehealth integration. Digital health adoption and localized wellness clinics are reshaping consumer expectations, forcing traditional storefronts to evolve into comprehensive community health hubs rather than mere medicine dispensaries.
How did the COVID-19 pandemic affect the Pharmacies and Drug Stores Market and its recovery trajectory?
The pandemic transformed pharmacies into critical public health bastions, accelerating diagnostic testing and vaccine administration mandates worldwide. While front-end retail sales initially dipped due to lockdowns, the sector leveraged its clinical infrastructure to secure a robust post-pandemic recovery, cementing its role in decentralized public healthcare delivery and immunizations.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The landscape is highly consolidated, dominated by retail giants like CVS Health Corporation, Walgreens Boots Alliance Inc., and AS Watson Group. These market leaders leverage massive scale, proprietary insurance partnerships, and sophisticated supply chains to squeeze out independent competitors while aggressively expanding into digital health and primary care clinics.
Executive summary: High-level synthesis of key findings about the Pharmacies and Drug Stores Market
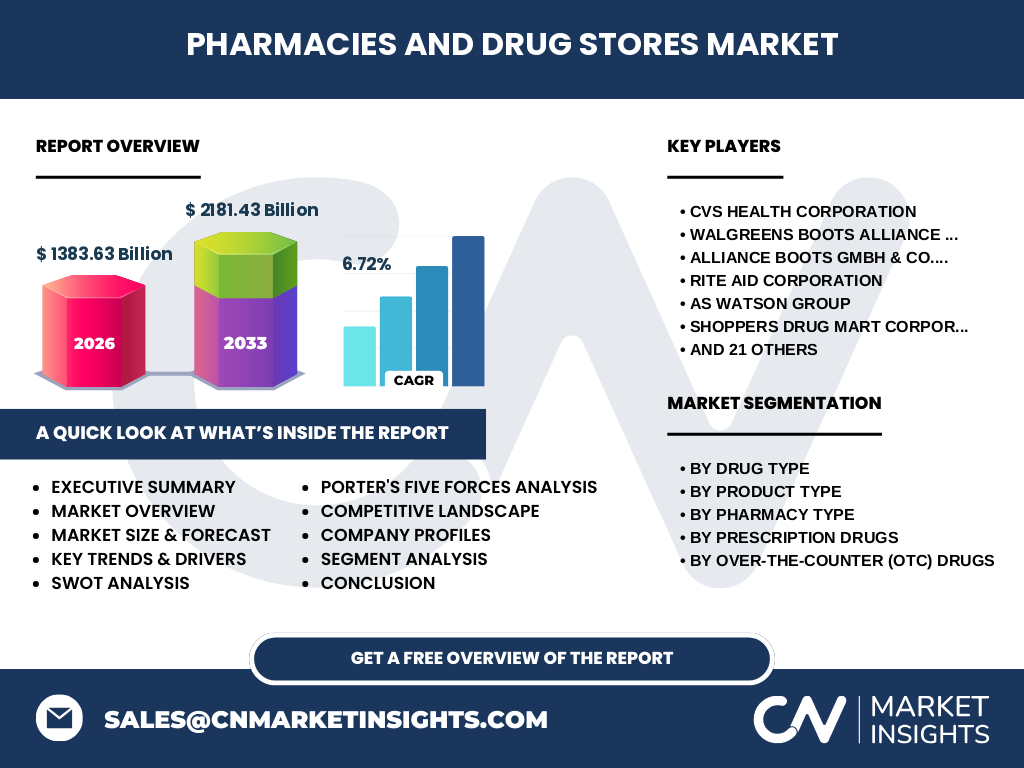
Driven by robust demand for specialty therapeutics and an expanding retail health footprint, the market is poised for significant expansion. Our research reveals a projected market size reaching 2181.43 Billion by 2033, expanding at a steady 6.72% CAGR from its 2026 baseline of 1383.63 Billion.
Market forecast: Projected growth from 2027 to 2033
The data suggests sustained, upward momentum as the sector transitions through the forecast period. Moving from 1383.63 Billion in 2026 to the forecasted 2181.43 Billion by 2033 at a 6.72% CAGR, growth will be propelled by high-margin specialty drug demand and aging populations requiring continuous therapeutic management.
Segmentation analysis of the Pharmacies and Drug Stores Market
The market breaks down across several vital vectors: Drug Type (Prescription Drugs, Over-The-Counter Drugs), Product Type (Skin Care, Cold and Flu, Dental, Weight Loss, Vitamins, Other), Pharmacy Type (Community, Hospital, Clinical, Compounding, Consulting, Ambulatory Care, Home Care), alongside specialized sub-segments like generic, brand-name, and specialty drugs.
Regional market analysis and geographic distribution
Geographically, the market is anchored by mature healthcare infrastructures in North America and Europe, while Asia-Pacific emerges as the fastest-growing region. Regulatory frameworks, localized reimbursement policies, and varying degrees of digital health integration heavily dictate performance differentials across these distinct global territories.
In-depth regional review of key operational markets
North America commands the largest revenue share, sustained by high per-capita healthcare expenditure and established retail pharmacy chains like Rite Aid Corporation and Shoppers Drug Mart Corporation. Meanwhile, Asia-Pacific markets like Japan and China demonstrate rapid adoption of corporate pharmacy models through firms such as Matsumotokiyoshi Holdings Co. Ltd. and China Nepstar.
Company profiles and strategic positioning of leading enterprises
Industry leaders maintain distinct competitive moats: CVS Health integrates pharmacy benefits with retail clinics, whereas Walgreens Boots Alliance focuses on international retail footprints and strategic healthcare investments. Specialty and institutional providers like PharMerica Corporation and Omnicare Inc. capture lucrative long-term care and institutional dispensing niches.
Porter's Five Forces analysis of competitive pressures
Supplier power remains moderate due to the consolidated nature of pharmaceutical manufacturing, whereas buyer power is high, driven by powerful insurance payers and price-sensitive consumers. The threat of substitution is low for prescription drugs but high for front-end OTC products, while competitive rivalry among major chains is intense.
SWOT analysis of the Pharmacies and Drug Stores Market
Strengths include trusted community presence and essential service status. Weaknesses involve razor-thin retail margins. Opportunities abound in clinical service expansion and digital therapeutics partnerships. Threats stem from aggressive e-commerce pharmaceutical entrants, stringent regulatory compliance costs, and unpredictable drug pricing reforms enacted by government bodies.
Value chain analysis from pharmaceutical manufacturers to end-users
The value chain initiates with active pharmaceutical ingredient sourcing and drug manufacturing by major pharma labs, moving through wholesale distributors to retail pharmacy operators like MedPlus Health Services Inc. and Apollo Pharmacy Limited. Final value realization occurs at the point of dispensing, where pharmacists counsel patients and ensure therapeutic compliance.
Investment insights and high-potential growth areas
Investors should target entities investing in digital health transformation, compounding pharmacy services, and localized ambulatory care integration. Companies that successfully diversify away from pure retail product sales into clinical service delivery will capture superior margins throughout the forecast period ending in 2033.
Conclusion and key takeaways for market stakeholders
The Pharmacies and Drug Stores Market is undergoing a structural evolution from transactional retail to comprehensive clinical care. With a projected valuation of 2181.43 Billion by 2033, operators must embrace omnichannel capabilities, specialty drug competencies, and strategic consolidation to survive margin erosion and thrive in the modern healthcare ecosystem.
Research methodology: How baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with industry executives, and secondary macroeconomic indicators from global health organizations. This multi-layered approach ensures precise sizing of the 1383.63 Billion market baseline and reliable forecasting up to 2033.
Scope of the report and analytical coverage parameters
This report covers global revenue performance, volume metrics, and strategic positioning within the Pharmacies and Drug Stores Market from 2026 to 2033. Analysis is strictly bounded by commercial retail, clinical, and institutional dispensing operations, excluding direct pharmaceutical manufacturing plants and raw chemical synthesis facilities.
Recent developments, corporate announcements, and strategic moves
Recent industry activity highlights aggressive mergers, acquisitions, and technological investments by key players such as Progressive Care Inc. and Discount Drug Mart Inc. Major operators are continuously forging strategic partnerships with telehealth platforms and implementing automated dispensing technologies to optimize operational efficiencies and offset escalating labor costs.